Market overview and structural significance of the K-12 Textbook Market
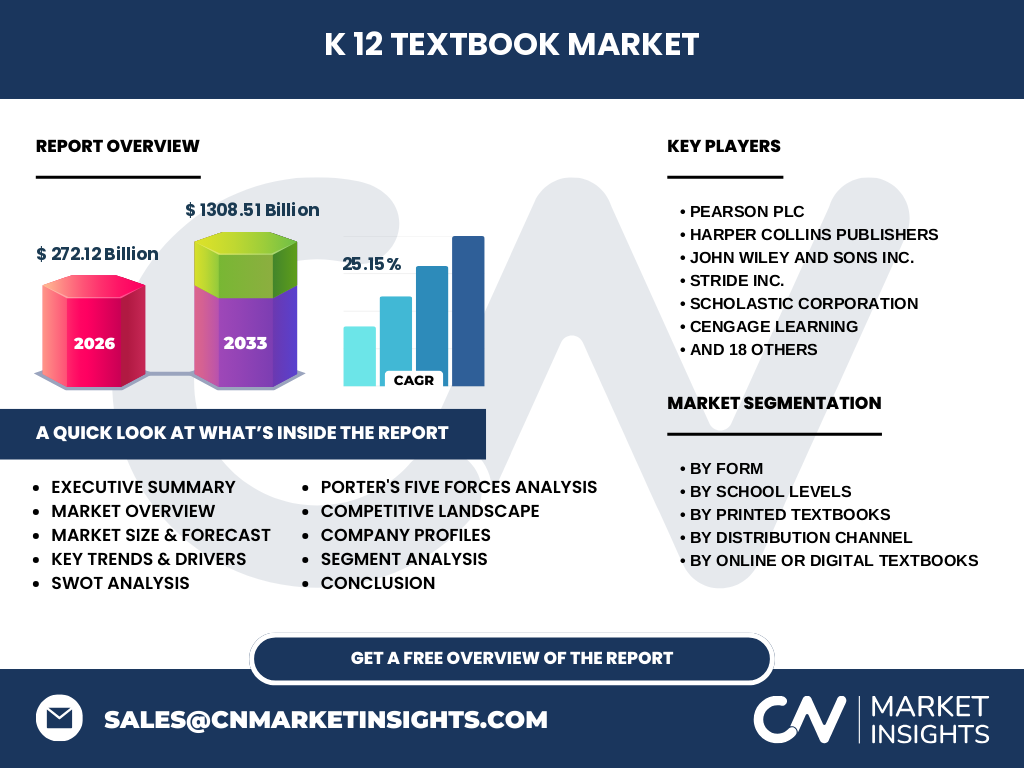
Our analysis indicates that the K-12 Textbook Market represents a foundational educational ecosystem valued at $272.12 Billion in 2026. This sector governs instructional material distribution across primary and secondary tiers, balancing traditional paper manufacturing with digital publishing innovations led by foundational participants like Pearson plc and McGraw-Hill Education.
What core factors drive and restrain the K-12 Textbook Market industry trends?
Structural growth relies on surging digital adoption, yet state-level adoption hurdles and paper supply chain constraints act as major restraints. Educational bodies enforce stringent curriculum compliances, favoring tech-enabled publishers such as Cengage Learning and Houghton Mifflin Harcourt who navigate institutional procurement cycles successfully.
The Shift Toward Omnichannel Learning and Emerging Patterns
The market experiences rapid migration toward cloud-based textbooks and interactive digital modules. Subscription-based digital textbooks and open educational resources are transforming classroom delivery, compelling industry innovators like Discovery Education and Edmentum Holdings Inc. to expand their multimedia portfolio offerings.
How did pandemic disruptions reshape the K-12 Textbook Market market size and recovery?
COVID-19 permanently altered educational delivery, accelerating remote learning investments by three to five years. Educational institutes pivoted aggressively toward digital infrastructure, driving structural demand for platforms managed by Stride Inc. and Blackboard Education as schools recovered through hybrid frameworks.
Competitive Benchmarking and Strategic Dynamics in Publishing
The competitive landscape remains moderately consolidated, featuring legacy giants like Harper Collins Publishers alongside specialized digital disruptors. Strategic mergers, localized textbook customizations, and platform acquisitions dictate market share as firms compete for multi-state district contracts.
Executive summary of key findings for the K-12 Textbook Market analysis
Proprietary research confirms explosive sector expansion, projecting the market to surge from $272.12 Billion in 2026 to $1308.51 Billion by 2033 at a CAGR of 25.15%. This growth is anchored by digital transformation across primary and secondary school levels.
Projected Growth Trajectory: K-12 Textbook Market Forecast (2027 to 2033)
Our forecast models exceptional momentum, driving the valuation from 2027 through 2033 to reach $1308.51 Billion at a 25.15% CAGR. Accelerated cloud deployment and interactive e-books fuel this unprecedented expansion across global school districts.
Segmentation analysis across formats, school levels, and distribution channels
The sector splits across printed and digital formats, encompassing primary and secondary school levels. Distribution relies on educational institutes, brick-and-mortar storefronts, and online retail channels. Key segments include Hardcover Textbooks, E-Books, and Custom Or Localized Textbooks tailored to specific curricula.
Geographic distribution and regional performance dynamics
Regional performance varies based on local government education budgets, digital infrastructure readiness, and textbook adoption mandates. North America leads in digital adoption, while Asia-Pacific shows rapid growth in primary and secondary enrollment figures, boosting brick-and-mortar and digital channel sales.
In-depth regional review of institutional procurement and policy constraints
State-level adoption committees heavily influence regional performance, dictating purchasing timelines and content standards. Regulatory compliance in major purchasing regions requires publishers like Savvas Learning Company and Scholastic Corporation to maintain localized compliance teams for institutional distribution.
Strategic positioning of leading companies in the K-12 Textbook Market
Market leaders employ diversified strategies combining traditional print longevity with SaaS-based digital learning tools. Companies like John Wiley And Sons Inc., Renaissance Learning Inc., and Imagine Learning LLC capture high-margin segments through adaptive assessment and subscription-based digital textbooks.
Porter's Five Forces assessment of industry competitiveness
Supplier power remains moderate due to paper and printing commodity costs, while buyer power is high among consolidated school districts. Threat of substitutes is mitigated by strict curriculum alignment, though threat of new digital entrants remains elevated due to open educational resources.
SWOT analysis of the global publishing and educational technology sector
Strengths include deeply established school district relationships and robust curriculum libraries. Weaknesses involve legacy print supply chain vulnerabilities. Opportunities lie in multimedia-enhanced digital textbooks, while threats include cybersecurity risks and strict federal data privacy regulations.
Value chain analysis from raw materials to end-user educational institutes
The value chain originates with raw paper and pulp sourcing, moving through authoring, editorial review, and printing or digital conversion. Distribution flows through educational institutes and online retail, ultimately delivering custom or localized textbooks to students.
Investment insights and high-potential areas for capital deployment
High-potential capital allocation centers on cloud-based textbooks, interactive digital publishing platforms, and specialized analytics tools. Investors should target firms demonstrating scalable subscription models and strong compliance integration with major school districts.
Conclusion and strategic takeaways for industry stakeholders
The market demonstrates phenomenal growth potential, scaling to $1308.51 Billion by 2033. Stakeholders must prioritize digital transformation, hybrid learning readiness, and strategic partnerships to capture market share in this fast-evolving landscape.
Research methodology for baseline estimation and data triangulation
Our methodology triangulates primary stakeholder interviews with educational publishers, trade registry data, and secondary macroeconomic indicators. Quantitative models cross-reference district procurement budgets against historical publishing output to establish precise baseline estimates.
Scope of the report, coverage parameters, and analytical limitations
This report covers global K-12 textbook publishing across printed and digital mediums from 2026 to 2033. Limitations include potential variance in localized municipal education budgets and unforeseen regulatory policy shifts affecting institutional procurement schedules.
Recent developments, corporate partnerships, and strategic product launches
Recent industry momentum is defined by strategic partnerships between educational publishers and tech providers. Companies like Teacher Created Materials, Goodheart Willcox Co. Inc., and OverDrive Education continue launching cloud-based and interactive reading platforms to meet modern classroom demands.